Britain’s Grid and Infrastructure Catch-Up: How Far Behind We Are, and What It Will Take
The UK’s biggest energy constraint is no longer generation. It is the wires. We have wind farms we pay to switch off, projects waiting up to a decade for a connection, and a transmission network that has barely grown in thirty years. The good news is that the catch-up has started, at a scale not seen since the grid was first built in the 1950s and 60s. The harder news is how much of it still has to land between now and 2030.
This analysis from Eleven Managing Director Dominic Kendal looks at three things: how far behind we are, what is being built and funded right now, and how big the remaining gap is.
How far behind we are
The clearest sign of the backlog is the connection queue. By the time reform began, more than 700GW of projects were waiting to connect: roughly four times what Britain needs by 2030, with some projects quoted dates up to ten years out (NESO). The National Audit Office found that the share of projects getting a timely connection fell from 64% in 2019-20 to just 16% in 2023-24 (NAO).
The root cause is decades of underbuilding. The generation mix moved north and offshore, to Scottish wind and North Sea farms, while the network was still shaped around coal plants near English cities. National Grid put the scale bluntly: it must build more than five times as much new transmission in six years as was built in the previous thirty (National Grid).
The cost of that gap is already on bills. When the wires can’t carry power south, the system operator pays Scottish wind farms to switch off and gas plants nearer demand to switch on. Constraint costs were around £1.5bn in 2024 and £1.9bn in 2025-26, and the NAO warns they could reach £7.8bn a year by 2030 without concerted action (Power Technology; NAO).
What’s being built now
Construction is now visible on the ground and on the seabed. The flagship is the Eastern Green Link programme: subsea HVDC “superhighways” that bypass the congested onshore corridor between Scotland and England. EGL2, a 2GW link from Peterhead to Drax built by SSEN Transmission and National Grid with Prysmian, entered its major construction phase in July 2026 and is due online in 2029, enough to supply around two million homes (SSEN Transmission; IndexBox). EGL1 is also under construction, and a fifth link is already in development (Construction Enquirer).
Behind the headline projects sits a wider pipeline. The NAO counts 88 transmission projects tied to the 2030 plan: 12 are complete, 12 have been folded into newer schemes and 64 are in progress. Twenty-six run through Ofgem’s Accelerated Strategic Transmission Investment (ASTI) route, which lets network companies skip parts of the usual approval cycle (NAO summary).
The queue is being cleaned up too. NESO’s Gate 2 reform, approved by Ofgem in April 2025, re-ordered connections around project readiness and what the 2030 plan actually needs. By August 2026, offers covered more than 60% of the projects required for 2030; in June that stood at 58%, over 700 projects and 37GW (The Planet Brief).
Where the money is coming from
The investment case has shifted from “whether” to “how fast”. In December 2025 Ofgem’s RIIO-3 final determinations approved £28bn of network spending for 2026-2031, which it expects to rise to around £90bn as further projects are approved through the period (Ofgem). The key commitments:
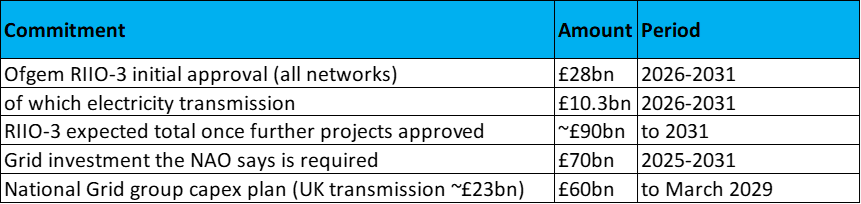
National Grid backed its plan with a £7bn rights issue in May 2024 (National Grid).
Consumers pay for this through network charges. Ofgem puts the gross bill increase at £108 by 2031, or around £30 net once lower constraint costs are counted. The NAO estimates electricity network charges alone will rise by about £60 by 2030 (NAO). The argument for spending now is that delay costs more: every year a link is late, constraint payments keep running.
How much is still to do
The gap between what is funded and what is finished remains large. NESO’s Clean Power 2030 advice said more than twice as much new transmission must be built in five years as in the whole of the last decade (Institute for Government). Most of that is still in development or early construction.
The NAO’s September 2026 review is a useful reality check. Many of the 64 live projects face significant risk to their forecast dates, and there has been no significant acceleration of the three projects NESO flagged in 2024 as most important for cutting constraint costs (NAO summary). It also found that many upgrades were chosen because they were already in development, not through a systematic assessment of need.
And 2030 is a waypoint, not the finish line. NESO has recommended around £89bn of further grid investment beyond 2030 (NAO, para 1.23), before counting the distribution upgrades needed for heat pumps, EV charging and data centres at the local level.
What it will take
Money is no longer the main constraint. Delivery is. Three bottlenecks will decide whether the pipeline turns into steel and cable on time:
- Planning and land. The NAO found that securing land rights alone can add up to three years to a project. Consenting reform has to show up in faster decisions, not just new guidance.
- Supply chain. Demand for HVDC cable, transformers and switchgear is outstripping global supply, and Britain is competing with Germany, the Netherlands and the US for the same factory slots. Ofgem now lets network owners order some equipment before consent, which helps but also shifts risk.
- People. The NAO names a shortage of skilled workers as a direct brake on delivery. This is the hardest bottleneck to fix quickly, and it gets its own section below.
The people problem
The grid will be built by people, and there are not yet enough of them. Energy & Utility Skills estimates the electricity sector workforce could grow from around 160,000 roles to nearly 290,000 by 2030 (Electrical Review). That is roughly 130,000 extra people in five years, in a labour market that already struggles to fill engineering roles.
The network companies are hiring at a pace not seen in generations. ScottishPower called it “the highest rate of recruitment that we’ve seen in the transmission business since probably the middle of the last century”:
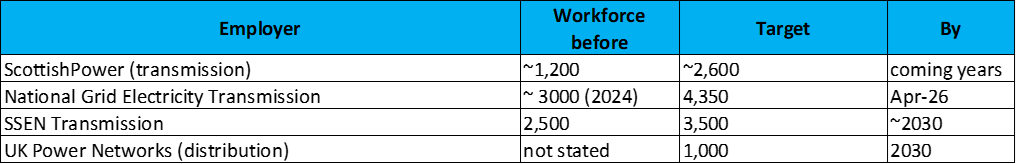
Source: Electrical Review, Jan 2026
The gaps are sharpest in a few places. The government’s Clean Power 2030 skills assessment expects the largest shortfalls in degree-level specialists and engineers, senior managers, and multi-skilled craftspeople at Level 3 (DESNZ). It also names project managers, chartered surveyors, quality control, environmental professionals and maintenance fitters. On site, that means HV engineers, cable jointers, overhead linespeople, protection and control engineers, and the commercial and consents teams who get projects through planning.
Three pressures make this harder:
- An ageing workforce. DESNZ flags an ageing workforce in craft and engineering roles, so a large share of experience will retire just as demand peaks.
- Competition for the same people. Grid contractors are competing with offshore wind, nuclear, rail, water and data centres for the same electrical and civil talent, and with overseas grid programmes for specialists.
- Long training pipelines. An apprentice cable jointer or a graduate engineer takes years to become site-ready. People hired in 2030 will be too late for 2030.
Government has started to respond. Its Clean Energy Jobs Plan (October 2025) expects clean energy employment to double to around 860,000 by 2030, names 31 priority occupations including electricians and welders, and funds five new Technical Excellence Colleges plus up to £20m to help oil and gas workers move across (Electrical Review).
For employers, the practical lessons are clear. Transferable talent from oil and gas, the armed forces, rail and heavy construction is the fastest route to scale. Retaining experienced engineers matters as much as hiring new ones. And workforce planning has to start when a project is consented, not when it reaches the construction phase. The companies that secure their people early will be the ones that deliver on time.
For the construction and investment community, this is one of the largest and most secure infrastructure pipelines in the country, regulated, long-dated and politically backed. The question for the next five years is not whether the grid gets built, but whether it gets built fast enough to stop Britain paying for clean power it cannot use.
Solving the Talent Challenges in Grid & Infrastructure Projects
In summary, building these large-scale projects requires expertise across a wide range of disciplines, including engineering, project management, asset management, and sales. However, the industry is grappling with a shortage of talent, especially for highly specialised roles.
At Eleven, we understand that each stage of a grid and infrastructure project requires different skill sets, and finding the right talent can be a challenge.
For example, a development may require teams for specific projects but does not have the demand for full-time employees across all their initiatives. This means there is a need for flexible, highly skilled talent that can move between projects as required.
How Eleven Can Help
We specialise in delivering niche talent across challenging locations and ensuring compliance with local regulations. Our expertise in this space has helped companies like Acciona streamline their compliance processes while building out complex renewable energy infrastructure in remote regions.
Whether it's securing engineering talent for the design phase or hiring skilled project managers for construction, our talent solutions provide the support for every stage of grid and infrastructure project.
Learn more about which talent solution is best for your project or contact Eleven today to discuss how we can help you find the right talent for your grid or infrastructure project.